Deepseek
来自我们记者的行业洞察
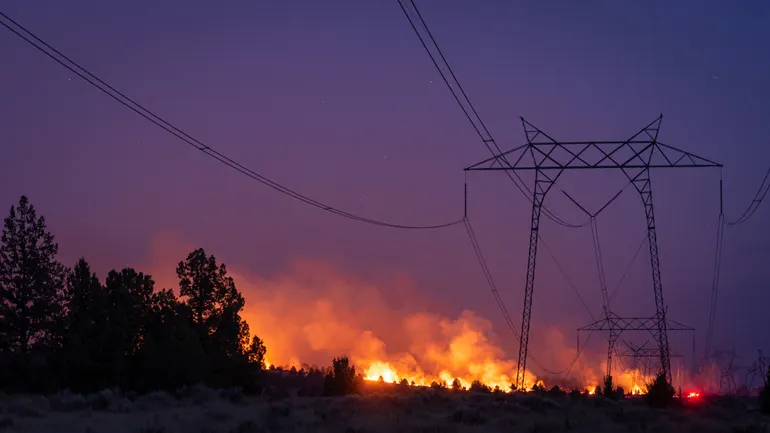
In 2023, wildfires across multiple regions of the United States caused massive losses, with utilities such as Xcel Energy and Hawaiian Electric facing severe litigation and insurance pressure. Insurance industry analysts are divided on whether the commercial insurance market can continue to provide wildfire liability coverage for utilities: one side believes risks can be managed through innovative products, while the other worries that government intervention will be needed to ensure grid stability. PG&E has already shifted to a fully self-insured model and relies on California's wildfire fund to address challenges.
U.S. utilities are preparing for a surge in clean energy integration in 2024. As wind and solar penetration increases, grid reliability faces new challenges. Xcel Energy, Eversource, and others are exploring solutions such as distributed energy resource management systems, grid-enhancing technologies, private LTE networks, and grid-forming inverters to optimize transmission and distribution system coordination and address demand peaks and frequency fluctuations.
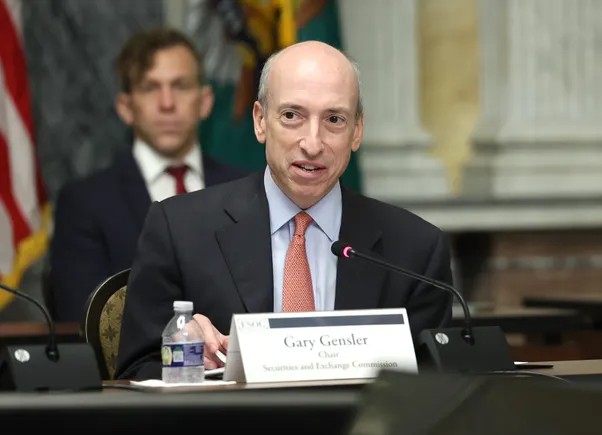
The SEC's climate disclosure rules proposed in March 2022 have sparked widespread controversy due to requiring companies to disclose Scope 3 emissions. The rule was originally scheduled for release in October 2023 but has been postponed to April 2024. Opponents argue that Scope 3 disclosure requirements are overly burdensome and exceed the SEC's authority, while supporters point out their alignment with EU and California regulations. Experts predict that Scope 3 provisions may be removed, but even if removed, Scope 1 and Scope 2 could still face legal challenges.
2023 was challenging for power companies: stock prices lagged the broader market, supply chain issues drove up renewable energy costs, and electricity prices rose for the third consecutive year. Looking ahead to 2024, the U.S. elections, high interest rates, and growing electricity demand will shape the industry landscape. This article synthesizes perspectives from Bank of America, Moody's, EIA, and other institutions to analyze electricity price trends, demand changes, interest rate impacts, and clean energy policy risks.
In 2023, U.S. solar added a record 33 gigawatts, and offshore wind delivered power to the grid for the first time. Despite challenges such as supply chains, tariffs, and interest rates, industry experts are optimistic about 2024, believing that investments from the Inflation Reduction Act will drive manufacturing reshoring, but transmission expansion and interconnection backlogs remain key bottlenecks.
Engineers from the North American Electric Reliability Corporation (NERC) and the Energy Systems Integration Group (ESIG) state that as the penetration of inverter-based resources (IBR) such as wind and solar increases and traditional synchronous units retire, the risk of grid frequency instability rises. Upgrading inverters with grid-forming (GFM) capability has become an urgent priority. This article reviews GFM technology principles, economics, prospects for battery energy storage applications, and progress in pilots and standards.
The Connecticut Public Utilities Regulatory Authority (PURA) has issued the final decision for the first phase of performance-based regulation (PBR), aiming to achieve policy goals and lower electricity rates, but utility companies such as Eversource warn that the current regulatory environment may be too stringent, harming investor capital attractiveness. The two sides have clear differences on core issues such as controllability and revenue mechanisms.
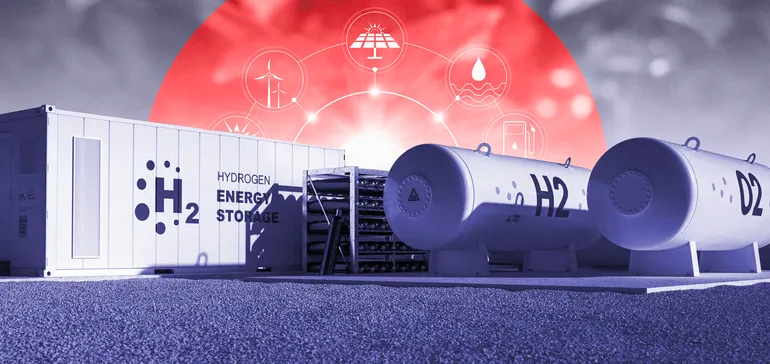
To achieve the 2035 power decarbonization goal, the United States is accelerating deployment of long-duration energy storage technologies beyond lithium-ion batteries. Since 2019, global long-duration energy storage projects have attracted over $58 billion in investment. Emerging solutions such as zinc-based, iron-air, hydrogen, and gravity storage are making progress in regulatory pilots and commercialization, but supply chains, infrastructure, and scalability remain key challenges.
Amid a severe backlog of interconnection requests from U.S. generators, ERCOT's "connect and manage" interconnection model has become a focus of reform. This model only studies local upgrade needs and addresses grid bottlenecks through market redispatch and curtailment, shortening the interconnection cycle to 1-2 years. From 2021 to 2022, ERCOT interconnected 14.2 GW, while PJM interconnected only 5.6 GW during the same period. However, experts point out that this model still faces challenges in operational issues such as voltage stability and short circuits, as well as transmission planning, making direct transplantation to other markets difficult.